Costs charged on every fold
Rolling folds with next-bar-open fills, gap-aware stops, spreads, square-root impact and borrow costs.
Every walk-forward fold pays trading costs, the Deflated Sharpe check gets stricter on every rerun, and each result shows its universe and assumptions.
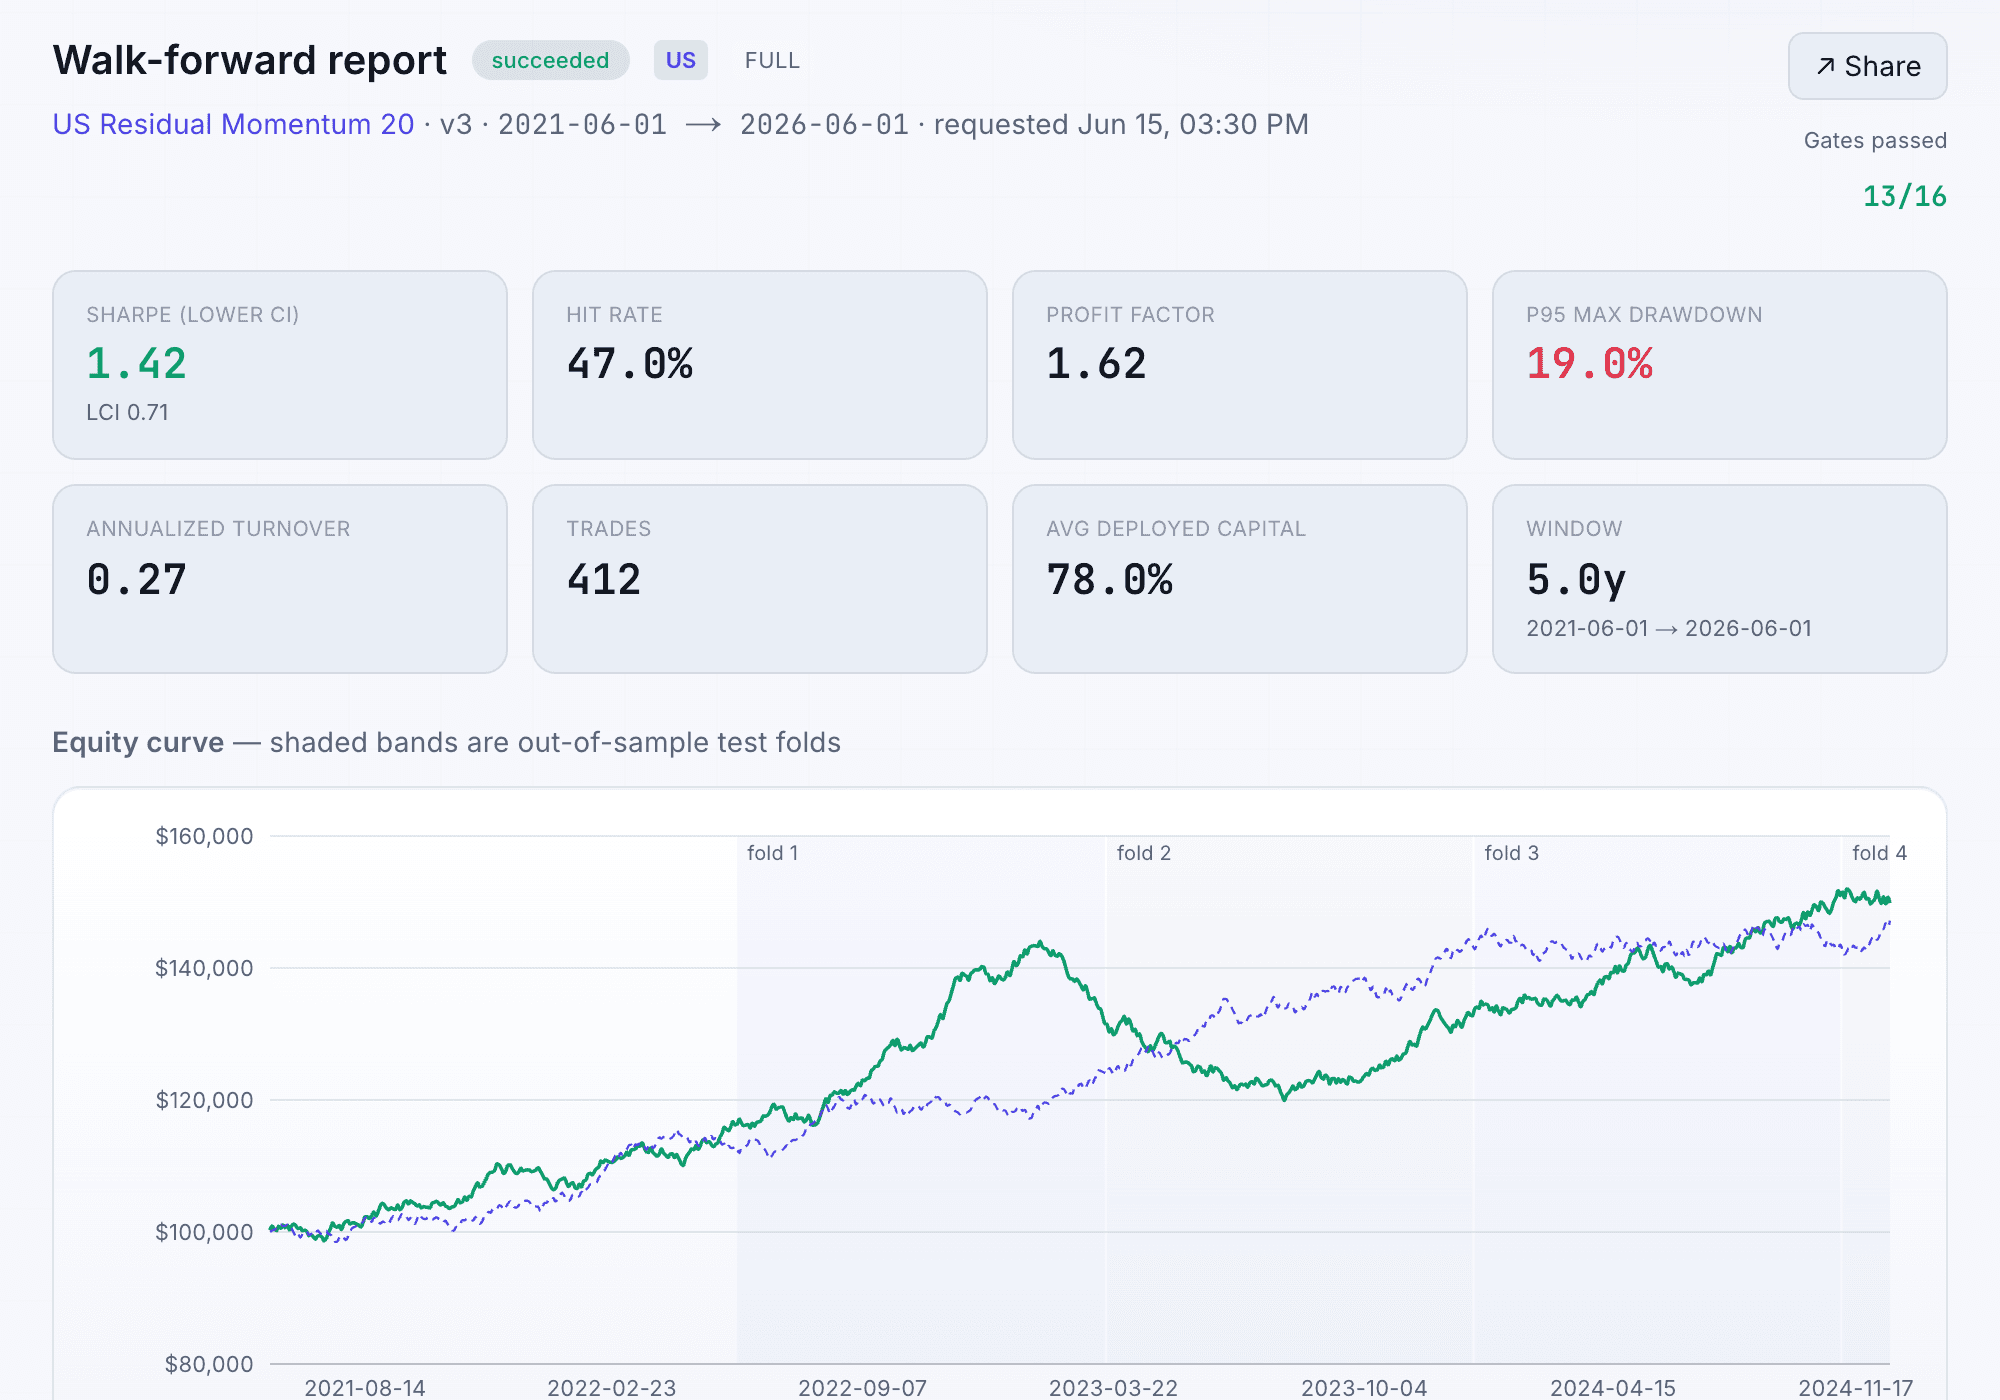
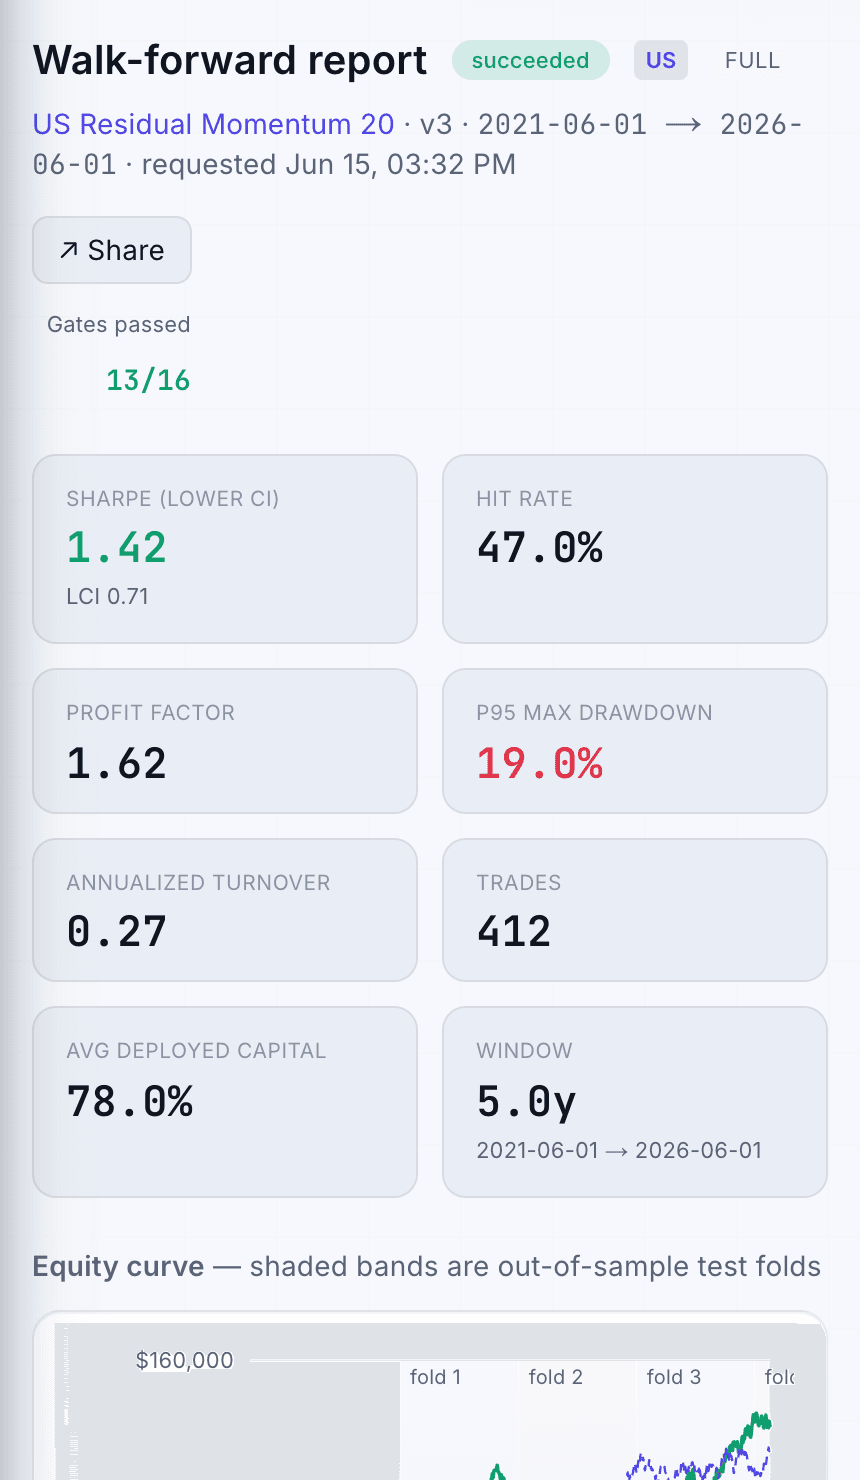
Walk-forward backtesting in the app at app.tradepolaris.com/backtests
Rolling folds with next-bar-open fills, gap-aware stops, spreads, square-root impact and borrow costs.
Equity curve vs the S&P 500, Sharpe/Sortino/Calmar, drawdown, VaR/CVaR, monthly heatmap and 6-factor attribution.
Probabilistic and Deflated Sharpe, minimum track record and overfitting probability separate edge from luck.
Use the visual builder, write Python or export the signals.
Whichever route you take, the backtest and the risk views read the same rules.
strategy: momentum-x-sectoruniverse: { region: US, top: 500 }signals: - momentum(126) - momentum(21) - filter: adx(14) > 20portfolio: { long: 50, weighting: risk_parity }exits: { trailing: 8%, invalidation: signal_flip }validate: { walk_forward: 5y, costs: realistic, gates: [DSR, PBO] }
Backtested / walk-forward results are hypothetical, do not represent actual trading, and are not indicative of future results.